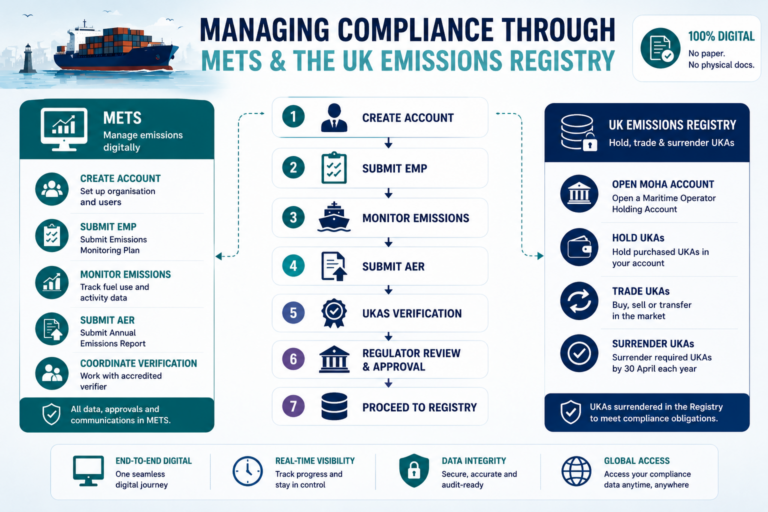
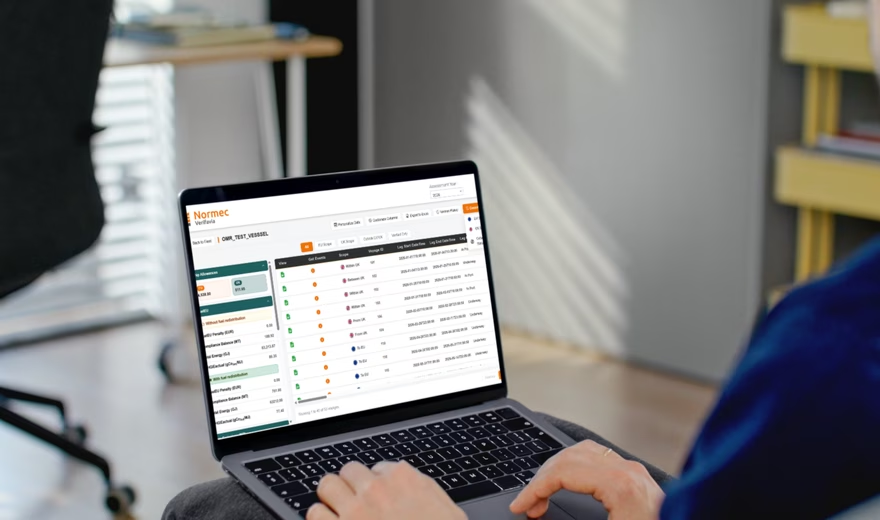
Unlike international maritime traditions, the UK ETS does not issue a physical, paper-based Document of Compliance (DoC) that must be kept on board ships. Instead, a fleet’s complete compliance history is digitally tracked and managed through two integrated web platforms:
METS (Manage the Emissions Trading Scheme): the central digital platform used by operators to create organizational accounts, submit emissions monitoring plans, coordinate with third-party verifiers, and submit verified data.
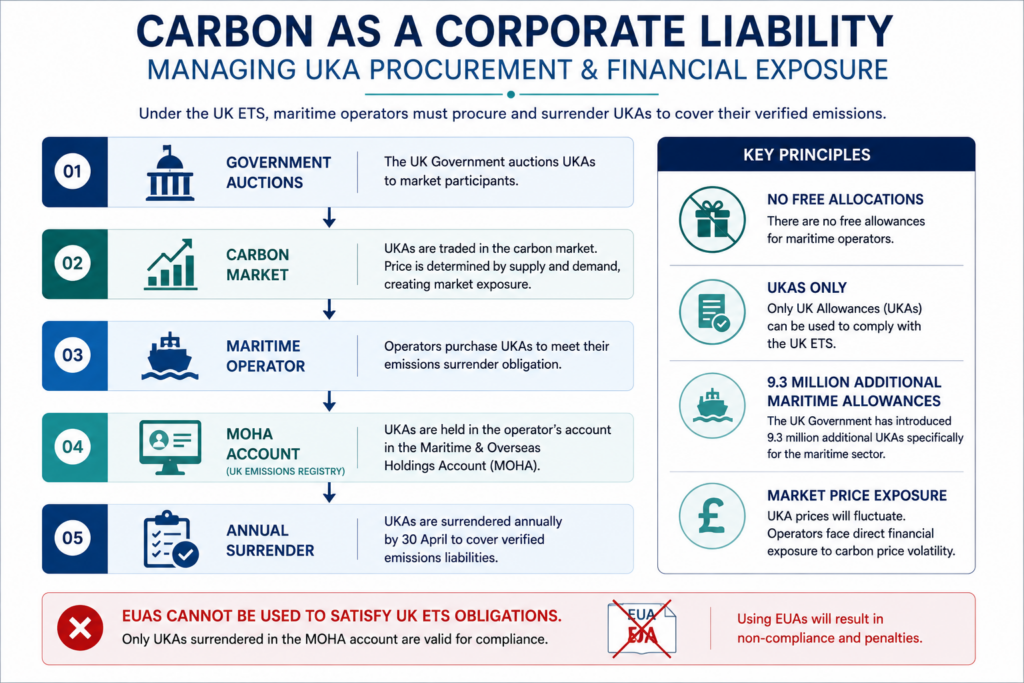
The UK Emissions Registry: the secondary trading portal where companies open a mandatory Maritime Operator Holding Account (MOHA) for storing, trading, and making the final annual surrender of CO₂ emission allowances.
Structural overview of assigned regulators
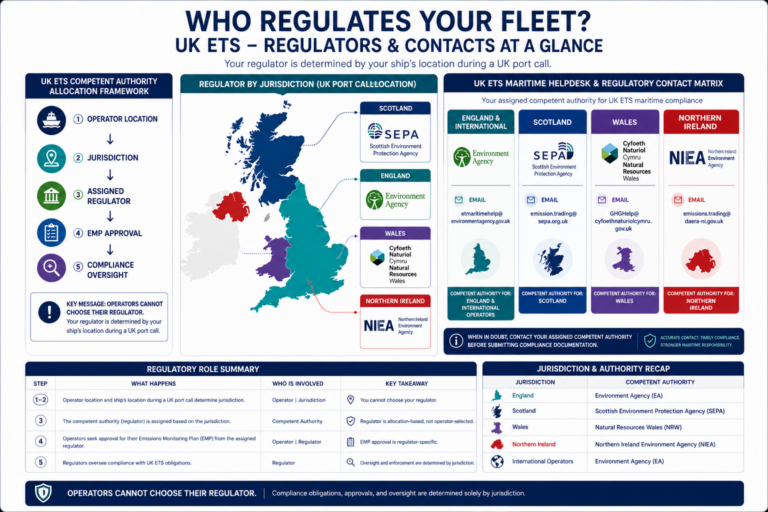
Shipping companies cannot choose their own supervisory authority. Each operator is assigned a specific competent UK national authority based on the company’s geographic location:
Operators with a registered address in the UK: are directly assigned to the national regulator for the region where their office is located (England, Scotland, Wales, or Northern Ireland).
International operators (without an address in the United Kingdom): are automatically assigned by default to the Environment Agency (EA) in England.
Matrix for Contact and Communication with Regulatory Authorities
Operators must use these official channels to create accounts and manage approvals of monitoring plans:
To avoid noncompliance, maritime operators must transition to a rigorous data management cycle.
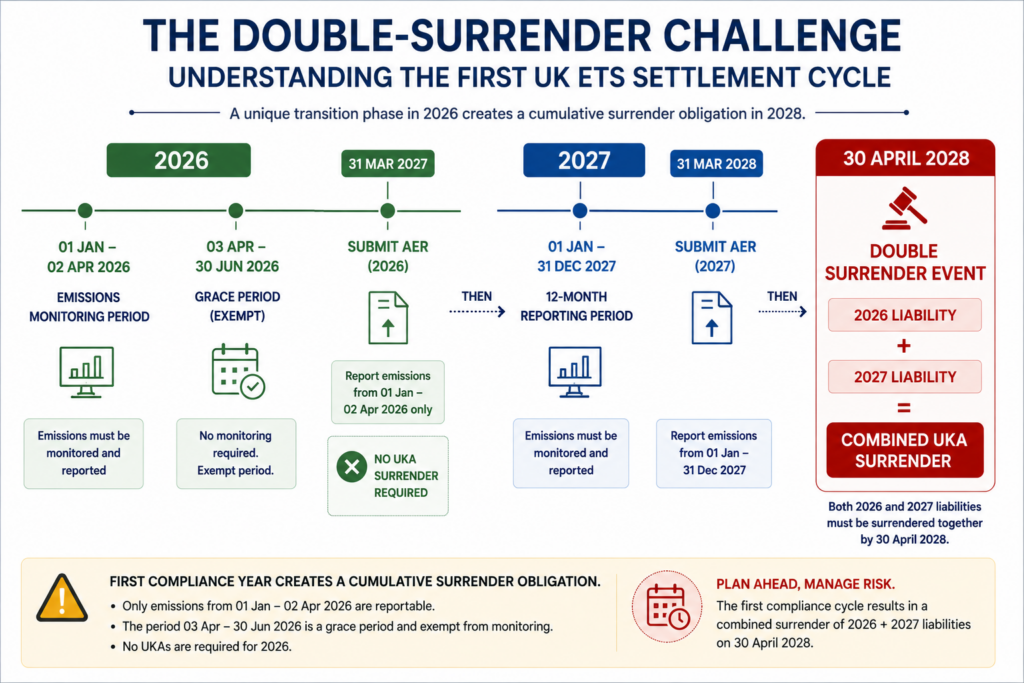
To protect operators from immediate cash flow problems during the transition, the UK authority has decoupled the deadlines for the first annual data reporting from the actual deadlines for surrendering emission allowances:
2026 Reporting Deadline: The verified AER covering the 6-month period from July 1 to December 31, 2026, must be submitted via METS no later than March 31, 2027. At this time, no emission allowances are yet transferred to the government.
2027 reporting deadline: The verified AER covering 12 months must be submitted via METS no later than March 31, 2028 .
The first combined surrender of emission allowances: On April 30, 2028, operators will face a combined “double surrender deadline.” Companies must simultaneously surrender UK emission allowances (UKAs) to the registry to cover their emission obligations for both the 2026 sub-period and the full calendar year 2027.
Financial Compliance – Purchasing Emission Allowances on the Market
Operating within the UK ETS makes CO₂ emissions a direct, volatile liability on the company’s balance sheet.
To integrate the shipping sector, the UK government is adding a total of 9,323,546 emission allowances to the overall UK ETS cap for Phase I (which runs through 2030). This volume is strictly aligned with the net-zero pathway of the UK’s strategy for decarbonizing the maritime sector.
No free allowances: Unlike the traditional manufacturing or aviation sectors, the maritime sector does not receive free CO₂ emission allowances. 100% of the adjustment to the maritime cap goes directly to government auctions.
Acquiring Emission Allowances: Operators must acquire UK emission allowances (UKAs) directly through official government auctions or open secondary carbon markets.
Warning regarding strict market separation: Operators cannot surrender EU emission allowances (EUAs) to cover a UK ETS liability. Purchasing an EUA to meet a UK compliance obligation is legally invalid and fully exposes the company to penalties for structural non-compliance.
The penalty for non-compliance
Compliance with the UK Emissions Trading System (UK ETS) is not limited to monitoring and reporting emissions. Operators must also surrender the required number of UK Allowances (UKAs) corresponding to their verified emissions. Failure to do so can result in significant financial penalties and ongoing compliance obligations. The penalties for failing to purchase and surrender sufficient UKAs by the annual deadline of April 30 are immediate and severe:
The penalty for excess emissions: A fixed civil penalty of £100 for every metric ton of carbon dioxide equivalent (CO2e) emitted and not covered—for which no emission allowance has been surrendered. Once noncompliance has been established, the competent authority will send a formal penalty notice to the responsible operator.
The repayment order: Paying the £100-per-metric-ton fine does not eliminate the original compliance debt. A common misconception is that paying the civil penalty resolves the compliance issue. This is not the case—
Even after the fine has been paid:
the underlying compliance obligation remains.
The shortfall in emission allowances has still not been settled.
The operator must still surrender the missing UKAs covering these emissions. The operator remains legally obligated to purchase and surrender the missing emission allowances during the subsequent calendar cycle, thereby increasing its market exposure.
Possible consequences beyond financial penalties
Failure to comply with UK ETS obligations can lead to consequences that go beyond the direct monetary fine, including:
Increased scrutiny by regulatory authorities and stricter enforcement measures.
Tightening of compliance measures by the authorities.
Reputational damage among customers, charterers, financiers, and other stakeholders.
Operators should therefore view the surrender of emission allowances as an essential compliance obligation and not merely as a financial obligation.
Division of Responsibilities Between Shipowners and Charterers
Given the commercial implications of complying with the UK ETS, shipowners and charterers must clearly define:
Which party is responsible for acquiring UK As.
How CO₂ costs are calculated and reimbursed.
Who is responsible for penalties resulting from non-compliance.
Procedures for sharing emissions data and settling CO₂ costs.
Clear contractual agreements help minimize disputes and provide certainty regarding financial responsibility.
The role of the BIMCO clauses
Standard clauses developed by BIMCO can assist parties in allocating responsibilities and costs related to the UK ETS.
These clauses may relate to, among other things:
Purchase obligations in the United Kingdom.
Mechanisms for reimbursing CO₂ costs.
Allocation of liabilities and penalties.
Requirements regarding information sharing between parties.
The use of well-drafted contractual provisions can significantly reduce the risk of disputes and unexpected financial risks.
Commercial cost recovery: pass-through clauses
Unlike previous industry proposals, the British government has made it clear that it will not provide a legal mandate for cost reimbursement or the pass-through of CO₂ costs to time charterers. The government expects commercial parties to address the treatment of CO₂ assets through standard contract law.
Since operational decisions (speed, route, and cargo) are typically determined by commercial charterers, ship managers and shipowners must proactively incorporate standardized CO₂ clauses, such as the BIMCO ETS allocation clauses, directly into charter party agreements to ensure seamless commercial pass-through.
Do you want to create a safe and healthy work and living environment?
We test, inspect, and certify so that organizations can innovate safely, quickly, efficiently, and cost-effectively.
Related news articles
15 Jul 2026
Everything went smoothly: better communication with suppliers and customers
In today’s rapidly changing, compliance-driven world, communication is much more than a routine task; it is the bridge that ensures business operations run smoothly. Whether it involves collecting crucial documents such as material declarations (MD), supplier declarations of conformity (SDoC), or IHM-related reports: the quality and consistency of communication often determine how efficiently everything runs.
15 Jul 2026
Strategic Management of the Asset Lifecycle under the Hong Kong Convention: The Critical Need for Early Preparation for IHM and Readiness for Recycling
As the global ship recycling industry focuses on stricter compliance with the Hong Kong International Convention for the Safe and Environmentally Sound Recycling of Ships (HKC), the importance of proactive compliance planning for the inventory of hazardous substances (IHM) Parts I, II, and III has increased significantly across the entire maritime sector. The recent implementation of IMO Resolution MEPC.379(80), which introduced the 2023 Guidelines for the Preparation of the Inventory of Hazardous Materials, together with the most recent amendments to be adopted in April 2025 under MEPC.405(83) in April 2025, has further heightened the industry’s expectations regarding the identification of hazardous substances, the accuracy of documentation, and preparation for recycling.
13 Jul 2026
SBTi corporate Net-Zero standard V2.0: What changes and what it means for your business
The Science Based Targets initiative published Version 2.0 of its Corporate Net-Zero Standard on June 11, 2026, effective February 1, 2027. Used by more than 11,000 companies globally, the standard has been fundamentally rewritten. Here is what practitioners need to know.
10 Jul 2026
The EU Commission Adopts EFRAG’s Revised Sustainability Reporting Standards for ESRS: What It Means for Your CSRD Reporting
On 3 July 2026, the European Commission formally adopted the Delegated Act containing the revised (simplified) European Sustainability Reporting Standards (ESRS), the detailed reporting framework for companies subject to the Corporate Sustainability Reporting Directive (CSRD). The adoption follows EFRAG’s final technical advice, submitted on 3 December 2025, and a public consultation on the Commission’s draft in May–June 2026. A separate Delegated Act establishing a voluntary sustainability reporting standard for undertakings outside the CSRD’s scope was adopted at the same time.
10 Jul 2026
SAF and RTFO: The Certificate Is Only as Good as What's Behind It
RTFO and the SAF Mandate are the UK’s two principal schemes for reducing transport fuel emissions.¹
- RTFO covers road transport, non-road mobile machinery and certain maritime renewable fuels.
- The SAF Mandate covers aviation, requiring SAF to reach 2% of UK jet fuel demand from 2025, rising to 10% by 2030 and 22% by 2040.²
Suppliers prove compliance with certificates tied to qualifying fuel or pay a buy-out price for any shortfall.
Both schemes work the same way: a supplier makes a sustainability claim, earns a certificate, and trades or redeems it against a target. Simple in theory—but only as solid as the claim behind it.
09 Jul 2026
India's carbon market enters its compliance era: What 490 obligated entities now face
As countries around the world strengthen climate policies to meet their Paris Agreement commitments, carbon markets have emerged as one of the most effective tools for reducing greenhouse gas (GHG) emissions. Recognizing this, India has established the Carbon Credit Trading Scheme (CCTS) the foundation of the Indian Carbon Market (ICM) under the Energy Conservation (Amendment) Act, 2022, with the scheme formally notified in June 2023.
09 Jul 2026
Beyond compliance: Is your market instrument ready?
As outlined in the accompanying article, the SBTi Corporate Net-Zero Standard Version 2.0 takes a more structured approach to market instruments and sets clearer conditions for how they may support decarbonisation. The more practical question for companies is what this means for programme design, evidence, and claims.
Sign up for the newsletter
Stay up to date on the latest news, exclusive updates, and valuable insights.