Compliance with the ReFuelEU Aviation Regulation in 2025: Verification Scope and Compliance Patterns
ReFuelEU Aviation (Regulation (EU) 2023/2405) is one of the European Union’s key measures to reduce aviation emissions by promoting the use of sustainable aviation fuels and discouraging economic refueling. For aircraft operators, Article 5(1) stipulates that at least 90% of the annual aviation fuel required for flights departing from an airport in the Union must be refueled at that airport in the Union. If this threshold is not met, Article 5(2) is invoked as justification, and EASA’s guidelines and monitoring tool support the monitoring and reporting process. The 2025 reporting year is also the first year in which competent authorities may impose penalties for non-compliance with Article 5(1) of the ReFuelEU Aviation Regulation 2023/2405.
In 2024, the first reporting year, the biggest challenge was setting up the monitoring and reporting process itself. By 2025, the picture has become clearer. The question is no longer just whether operators are reporting, but what the reports reveal about compliance behavior and the quality of the justifications provided. This is where this year’s verified information comes in handy.
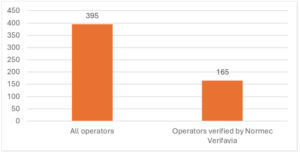
A total of 165 airlines were verified by Normec Verifavia under the ReFuelEU Aviation Regulation for the 2025 reporting year, representing approximately 42% of all operators covered by the regulation. Together, these operators accounted for 22.54 million metric tons of aviation fuel required per year, 22.88 million metric tons of fuel refueled at airports within the Union, and 0.152 million metric tons of annual refueling volumes under fuel security rules.
Before delving deeper into the figures and compliance patterns, it is important to revisit how compliance with the ReFuelEU Aviation Regulation works.
Article 5(1) stipulates that an aircraft operator must refuel at least 90% of the required fuel at a Union airport. If this requirement is not met, Article 5(2) of the Regulation allows aircraft operators to justify the corresponding “unrefueled quantities” reported in Column H (Annual unfueled quantity under fuel safety rules). This provision acknowledges that an operator may not always be able to meet the 90% requirement due to operational constraints or other legitimate operational reasons.
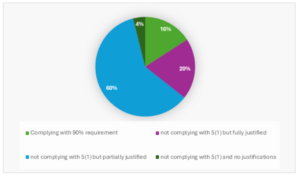
The compliance results reveal several clear compliance patterns that go beyond a simple assessment of “compliant” or “non-compliant.” Of the audited group, 16% of operators complied with Article 5(1) by meeting the 90% refueling requirement. 20% of the operators did not meet the 90% threshold but were able to account for all unreplenished quantities. 60% of operators could justify only a portion of the reported refueling shortfall, while 4% of operators could not justify the refueling shortfall at all.
This provides a more realistic picture of how ReFuelEU Aviation functions in practice. The verified figures show that full compliance remains difficult for many operators, but they also demonstrate that non-compliance does not always indicate a weak case. In many cases, the issue is not the existence of unfueled quantities per se, but whether those quantities are justified in light of the “annual fueling quantities for fuel safety regulations” and are supported by accurate data recording and supporting evidence.
The key message from this initial layer of analysis is simple: compliance is not just about how much fuel has been dispensed, but also whether the operator can account for the difference when there are shortfalls.
We also note that the largest number of operators fall into the “partially justified” category, which implies that most operators had difficulty justifying all the unfueled quantities they encountered. This is where the quality of reporting becomes just as important as the operational result itself.
The Role of Justification Under Article 5(2)
One of the clearest patterns in the 2025 reporting year is that the quality of justification now makes the difference between operators with manageable non-compliance and operators at risk. Operators with a complete justification were generally able to demonstrate that the untanked volumes were related to operational or safety-related considerations and that the supporting evidence was available and traceable. In those cases, the verification process largely revolved around confirming that the explanation corresponded to the reported data. The more challenging cases involved partial justifications (where operators could justify unfueled quantities at some airports but not at all of them). These were the reports in which sufficient evidence was provided for some airports but not for others. In several cases, these usually point to gaps in record-keeping or inconsistent data collection, rather than a complete lack of an operational reason.
The smallest but most vulnerable group is the one that could not justify the unfueled quantities at all. In those cases, the report may still contain a reason for the refueling behavior, but without the evidence needed to substantiate it, the outcome remains weak from a compliance perspective.
Conclusion
This year’s ReFuelEU Aviation report provides valuable insights into how aircraft operators are implementing the regulation and demonstrating compliance. Although some operators at all relevant airports in the Union complied with the refueling obligation under Article 5(1), many invoked justifications under Article 5(2) to account for the fuel quantities that were not refueled. The results underscore the importance of sound record-keeping, accurate fuel data, and well-documented supporting evidence in demonstrating compliance.
Do you want to create a safe and healthy work and living environment?
We test, inspect, and certify so that organizations can innovate safely, quickly, efficiently, and cost-effectively.
Related news articles
17 Jun 2026
A Guide to SAF Documentation: Common Challenges and Best Practices
As the adoption of sustainable aviation fuel (SAF) under aviation regulations continues to grow, the quality and traceability of documentation have become key considerations in SAF reporting and verification activities. Although SAF offers significant environmental benefits, operators must maintain accurate, complete, and verifiable data throughout the entire reporting period to demonstrate compliance.
Based on our experience supporting aviation stakeholders in compliance and verification activities, several recurring challenges have emerged. Fortunately, many of these issues can be addressed through early planning and proactive collaboration with fuel suppliers and competent authorities.
18 Jun 2026
UK ETS: Consultation on the Treatment of Sustainable Aviation Fuel (SAF)
The UK Emissions Trading System (UK ETS) authority has launched a consultation to gather stakeholders’ views on the future treatment of SAF within the UK ETS framework, particularly in light of the introduction of the UK SAF mandate. The consultation examines potential changes to SAF eligibility criteria, sustainability requirements, greenhouse gas (GHG) reduction thresholds, and accounting methodologies, with the aim of strengthening policy alignment and supporting the decarbonization of the aviation sector.
18 Jun 2026
The Strategic Roadmap for 2026: The Path to Final Settlement of CORSIA Phase 1
The first phase of CORSIA is entering its final months. For most operators, the 2025 reporting cycle—which will be verified by independent bodies by April 30, 2026—represented the most demanding data processing operation since the program’s inception. However, a verified report is merely the “input” for a larger financial calculation.
As 2026 progresses, the sector is operating in a two-track reality:
Retrospective reconciliation: finalizing financial obligations for 2025.
Forward-looking monitoring: Ensuring that the 2026 emissions year—the final year of the first phase—is tracked with absolute precision in the run-up to the April 2027 verification deadline.
01 May 2026
ETS 2 First Verification Cycle Complete: Lessons from Early Implementation
ETS 2 verifications have now been completed for the first reporting cycle, marking an important milestone in the expansion of the EU carbon market to transport and building fuels.
01 May 2026
CSRD Scope Narrowed: But Are You Still Required to Verify Sustainability Reporting?
The European Commission’s Omnibus “Content Directive” entered into force on 18 March 2026, bringing final clarity to the Corporate Sustainability Reporting Directive after more than a year of negotiation. EU Member States now have until 19 March 2027 to transpose the changes into national law. For organisations subject to CSRD, this is the moment to adjust your verification planning with confidence. The question is no longer whether CSRD will apply it is whether your organization remains in scope, and if not, whether voluntary verification still serves your business objectives.
01 May 2026
EU Launches Carbon Removal Certification Framework (CRCF)
The European Union has taken a significant step toward achieving climate neutrality with the adoption of Regulation (EU) 2024/3012, establishing the Carbon Removal Certification Framework (CRCF).
01 May 2026
EU Greenwashing Crackdown: What EmpCo and Green Claims Mean for Environmental Marketing
The European Union is significantly tightening its rules on greenwashing through two complementary pieces of legislation: the Empowering Consumers for the Green Transition Directive (EmpCo) and the Green Claims Directive.
Sign up for the newsletter
Stay up to date on the latest news, exclusive updates, and valuable insights.
Related services
Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA)