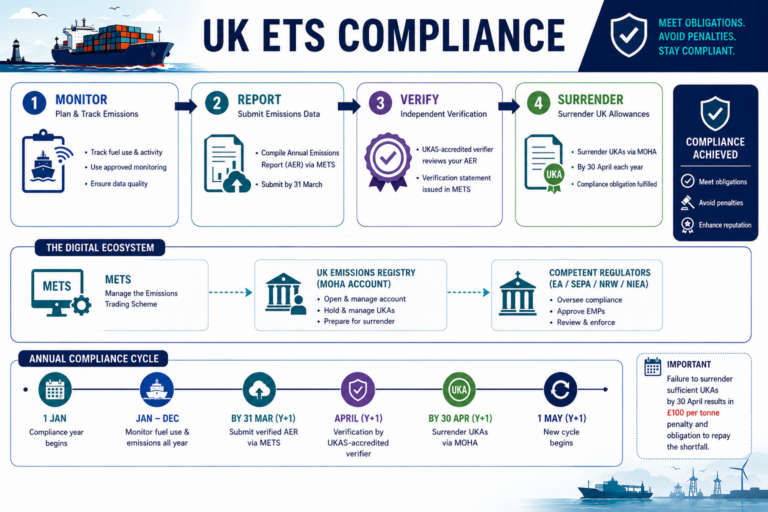
The maritime sector is heading into a highly fragmented era of emissions compliance. Following the phased introduction of the EU Emissions Trading System (EU ETS), the British government will officially expand the UK Emissions Trading System (UK ETS) to include the shipping sector starting July 1, 2026.
For shipowners, commercial charterers, and ship managers, carbon pricing is no longer just an EU matter, but is now also a domestic UK legal obligation. Regardless of a ship’s flag state, every commercial vessel with a gross tonnage (GT) of 5,000 or more that calls at a port under UK jurisdiction is legally required to monitor and report greenhouse gas (GHG) emissions and surrender emission allowances.
Key Principles: Scope, Geography, and Exemptions
The UK ETS for shipping is structured around precise vessel metrics, definitions of greenhouse gases, and geographic voyage parameters. Operators must understand these boundaries to accurately calculate their compliance obligations.
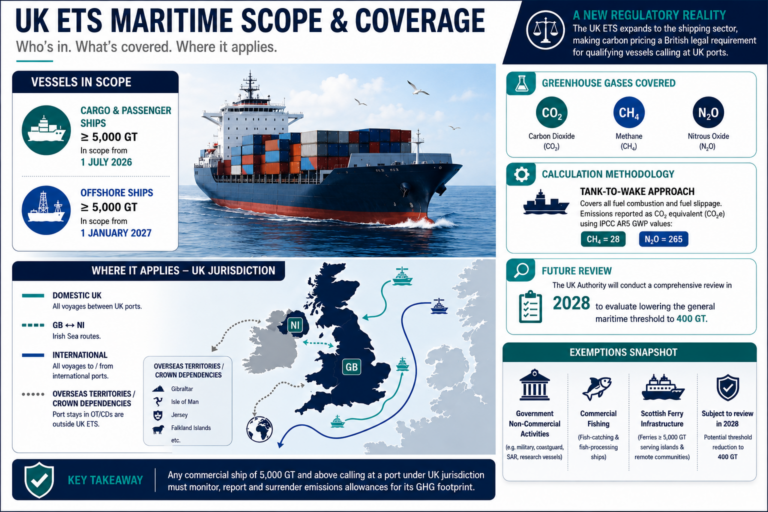
Ships falling within the scope
Cargo and passenger ships: The scheme strictly applies to cargo and passenger ships of 5,000 GT and above, effective July 1, 2026.
Offshore vessels: The inclusion of offshore vessels (5,000 GT+) has been intentionally deferred until January 1, 2027. This strategic delay explicitly aligns the UK’s timeline with the expansion of the EU ETS to offshore vessels, to prevent market disruptions or ships rerouting to avoid the scheme.
Emissions coveredby the scope
Gases covered: Compliance extends beyond carbon dioxide alone and includes carbon dioxide (CO₂), methane (CH₄), and nitrous oxide (N₂O).
Calculation framework: Emissions are assessed on a “tank-to-wake” basis, taking into account both combustion and fuel loss. To ensure accuracy in accordance with international reporting standards under the Paris Agreement, methane and nitrous oxide are reported on a carbon dioxide equivalent (CO₂e) basis, using the Global Warming Potential (GWP) figures from the IPCC’s Fifth Assessment Report (AR5) (CH4 = 28; N2O = 265).
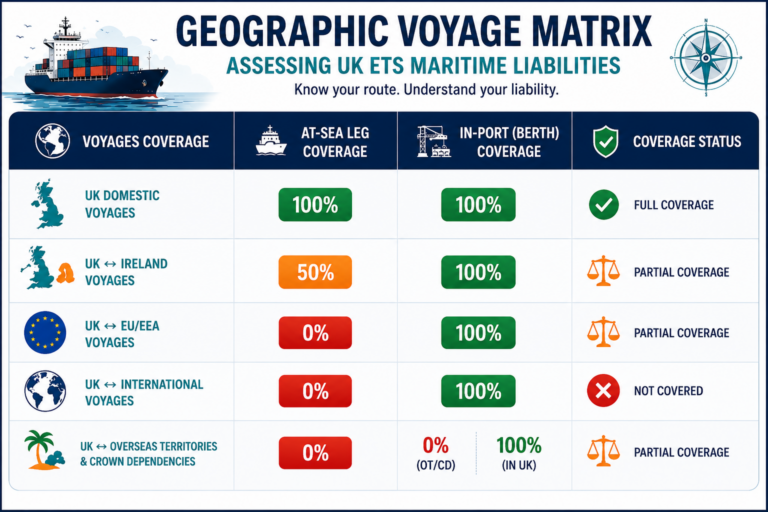
The regulations calculate a company’s total UK Allowances (UKA) based on specific voyage profiles:
Voyage Profile / Port of Call Location
Obligation for the sea voyage
Obligation in port (at the berth)
Regulatory context and cross-border nuances
Travel between UK ports (domestic)
100%
100%
Includes standard coastal voyages and “cruises to nowhere” that begin and end in the same British port.
Great Britain → Northern Ireland
50%
100%
Strategically applied with a 50% discount to prevent a difference in carbon prices across the Irish Sea and to eliminate the circumvention of routes via the Republic of Ireland.
British port → EU/EEA member state
0%
100%
The maritime leg is 0% under UK rules (note: the EU ETS covers 50% of this maritime leg). Stays in UK ports are 100% taxable.
UK port → International port
0%
100%
International sea legs are excluded from the outset. However, all fuel consumed while the ship is at anchor or moored in a UK port is included.
Voyages to and from British Overseas Territories / Crown Dependencies
0%
0% (in Overseas Territories/Crown Dependencies)/ 100% (in the UK)
Applies to routes involving jurisdictions such as Gibraltar, the Falkland Islands, the Isle of Man, or Jersey. Stays in ports within the overseas territories/Crown dependencies are fully exempt.
Exemptions from the UK ETS
The UK authority has established explicit legal exemptions from the UK ETS in a selective scenario—
Non-commercial government activities: Military, customs/border control, police, coast guard, search and rescue, firefighting, humanitarian aid, and government research vessels are fully exempt from reporting or surrender obligations.
Commercial fishing: Fishing vessels and fish-processing vessels are excluded to maintain alignment with the EU ETS, where fishing fleets remain outside the scope of CO₂ pricing.
Scottish ferry infrastructure: Ferries exceeding 5,000 GT that serve the Scottish islands and remote communities on the peninsula are exempt from the scheme. This protects vital supply lines from the impact on ticket and freight prices, in accordance with the legal provisions of the Islands (Scotland) Act 2018.
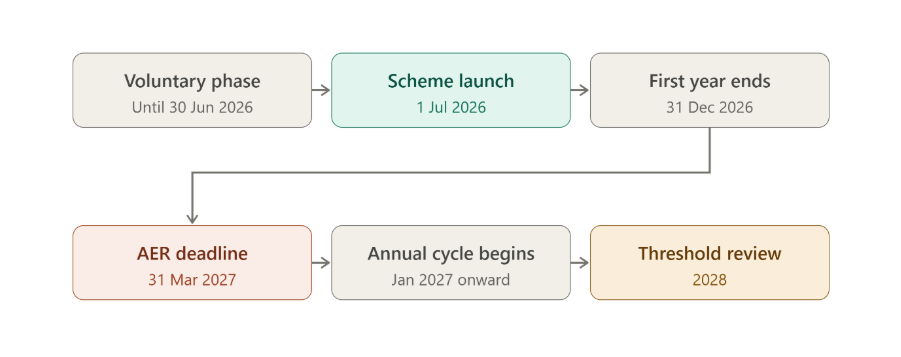
These core exemptions, along with the 5,000 GT threshold, are not permanent. The UK authority has commissioned a comprehensive system review in 2028, during which a formal assessment will be conducted to determine whether the general maritime threshold can be lowered to 400 GT.
Definition of the operator / responsible entity
A crucial step for a shipping company is to determine which legal entity bears the obligation toward the UK government.
The default entity: Legal and financial responsibility for compliance rests solely with the registered owner of the vessel.
The delegation mechanism: The registered owner may choose to formally delegate all compliance obligations under the UK ETS to an external ship management company—specifically the ISM company or the holder of the Document of Compliance (DOC).
The mandate document: For the delegation to be recognized, both parties must sign a legally binding, signed written agreement (mandate document). This mandate must be uploaded to the digital compliance system. If the regulator deems the documentation insufficient or missing, responsibility reverts to the registered owner.
To prevent non-compliance, maritime operators must adopt a rigorous data management cycle.
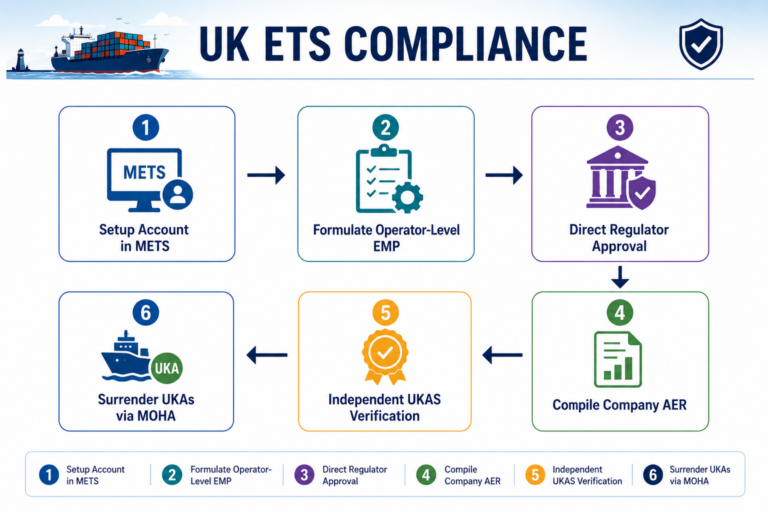
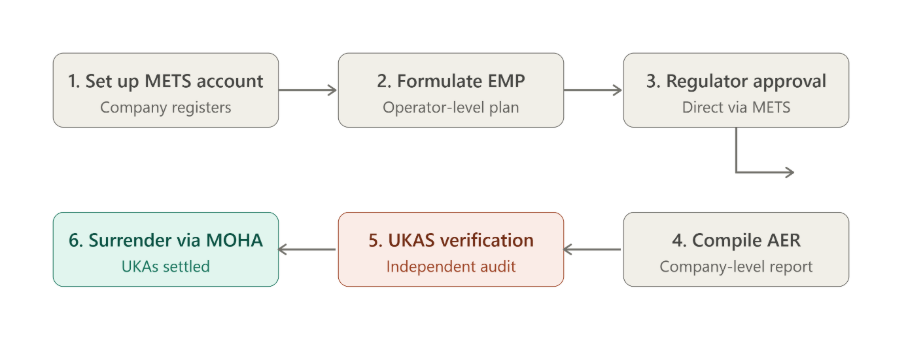
Step 1: Developing the Emissions Monitoring Plan (EMP)
Each maritime operator must prepare a technical Emissions Monitoring Plan (EMP) that defines fuel measurement instruments, source data recording, and vessel-specific parameters.
At the company level, not the vessel level: Operators do not submit separate plans for each vessel. They maintain a single company-wide EMP that lists and consolidates all of the company’s vessels covered by the scheme.
The approval process: Unlike traditional MRV and EU ETS systems, independent external verifiers are not required to review or approve the monitoring plan. The EMP is submitted directly via METS to the designated UK regulator, which has sole authority to grant approvals.
The 42-day rule: For every ship that joins a company’s fleet for the first time or commences an active voyage under British jurisdiction, the operator must formally request an amendment to or the creation of an EMP no later than 42 days after the start of that first maritime activity.
Changes to the Management Plan: Significant versus Non-Significant Changes
Amendment to the EMP, following approval
Significant changes
Application must be submitted 14 days in advance
Add a vessel to the fleet New or alternative fuel Changes to emission factors Reporting of emission reductions
Non-significant changes
Bundled; to be submitted by December 31
Updates to internal procedures Changes to contact information
Once an EMP has been approved, future changes are classified into different regulatory categories:
Significant changes (application required14 days in advance): Substantial changes require a formal application to amend the EMP, which must be submitted 14 days before the change takes effect. These include, among other things, adding a vessel to the fleet, introducing new or alternative fuel types (including sustainable biofuels), updating the fuel monitoring method, changing default emission factors, or using eligible fuel mechanisms for an Emission Reduction Claim (ERC).
Non-significant changes (annual deadline: December 31): Minor administrative adjustments, such as updating internal business procedures or changing the contact information for regulatory affairs, may be bundled and submitted as a single amendment request no later than December 31 of the calendar year in which they occur.
Step 2: Preparing the Annual Emissions Report (AER)
Operators must continuously track data throughout the calendar year to prepare an aggregated annual emissions report (AER). Like the monitoring plan, the AER is prepared strictly at the company level. It provides a detailed overview of fuel consumption figures per vessel, after which the company’s total emissions footprint is calculated mathematically.
Step 3: Independent Third-Party Verification
Before an AER can be submitted to the government, it must be reviewed and approved by an independent, commercial verifier that is explicitly accredited by UKAS (United Kingdom Accreditation Service). Verifiers review voyage logs and bunker delivery notes to confirm that the reported emissions align with the parameters in the monitoring plan approved by the regulator.
Timeline, Phasing, and the Grace Period for “Dual Submission”
The UK ETS uses a special onboarding schedule designed to give shipping companies ample time to adapt to the digital portals before significant financial expenditures occur.
2026
2027
2028
Through June 30: Voluntary phase
July 1: Start ofthe maritime scheme
March 31: AER deadline 2026 ( verified)
March 31: AER deadline 2027 ( verified)
April 30: First joint surrender of emission allowances
The first shortened scheme year
Voluntary phase (through June 30, 2026): The METS portal is fully accessible for creating accounts, familiarizing yourself with the software, and uploading EMPs for free. Monitoring plans that are “in principle” approved during this phase will automatically become formally active upon launch.
Official start (July 1, 2026): Compliance obligations for the shipping industry take legal effect. Operators must maintain records for a shortened regulatory year of six months running through December 31, 2026.
Standardization (starting in 2027): The scheme returns to a normal 12-month calendar cycle (January 1 through December 31).
Operational Action Plan for Operators
To ensure that everything is fully prepared before government enforcement takes effect, fleet directors and ship managers should immediately work through the following checklist:
Establish internal responsibility: Formally determine whether the registered owner or the ISM ship manager will act as the designated “maritime operator” for each vessel in the fleet.
Fully establish the legal mandates: If responsibility is delegated to an ISM manager, formal written mandate documents must be drafted and signed by the boards of directors of the companies involved.
Register for access to METS: Complete the online registration forms to create the company profile and gain immediate access to the portal. (Reference links: METS Part 1 Create an Account, METS Part 2 Log In 1 )
Onboard data providers: Formally select the company’s UKAS-accredited third-party verifier within the METS platform to enable automated data workflows.
Create a MOHA account: Complete the registry administrator’s onboarding steps to create a Maritime Operator Holding Account in the UK Emissions Registry in preparation for future purchases of emission allowances.
Develop the EMP at the company level: Collect technical specifications of the fleet and fuel recording methods to develop the aggregated monitoring plan at the operator level for approval. (reference link: METS Part 4 EMP Account Data, METS Part 4.1 Emissions Monitoring )
Update commercial charter agreements: Review all active time charter contracts to include transparent clauses regarding the allocation of carbon costs and data sharing.
Do you want to create a safe and healthy work and living environment?
We test, inspect, and certify so that organizations can innovate safely, quickly, efficiently, and cost-effectively.
Related news articles
18 Jun 2026
The 2026 strategic roadmap: Navigating the final reconciliation of CORSIA phase 1
The first phase of CORSIA is entering its final months. For most operators, the 2025 reporting cycle—verified by independent bodies before April 30, 2026, represented the most rigorous data exercise since the program’s inception. However, a verified report is merely the “input” for a larger financial equation.
As we progress through 2026, the industry is operating in a dual-track reality:
Retrospective Reconciliation: Finalising the 2025 financial obligations.
Prospective Monitoring: Ensuring the 2026 burn year, the final year of the first phase, is tracked with absolute precision ahead of the April 2027 verification deadline.
18 Jun 2026
UK ETS: Treatment of Sustainable Aviation Fuel (SAF) Consultation
The UK Emissions Trading Scheme (UK ETS) Authority has launched a consultation to gather stakeholder views on the future treatment of SAF within the UK ETS framework, particularly in light of the introduction of the UK SAF Mandate. The consultation explores potential changes to SAF eligibility, sustainability requirements, greenhouse gas (GHG) savings thresholds, and accounting methodologies, with the objective of strengthening policy alignment and supporting the decarbonisation of the aviation sector.
18 Jun 2026
ReFuelEU Aviation Compliance in 2025: Verification Coverage and Compliance Patterns
ReFuelEU Aviation (Regulation (EU) 2023/2405) is one of the European Union’s key measures to reduce aviation emissions by increasing the use of sustainable aviation fuels and discouraging economic tankering. For aircraft operators, Article 5(1) requires that at least 90% of the yearly aviation fuel required for flights departing from a Union airport is uplifted from that Union airport. Where this threshold is not met, Article 5(2) is used for justification, and EASA’s guidance and Monitoring Tool support the monitoring and reporting process. The 2025 reporting year is also the first in which competent authorities can impose penalties for non-compliance with Article 5(1) of the ReFuelEU Aviation Regulation 2023/2405.
In 2024, the first reporting year, the main challenge was establishing the monitoring and reporting process itself. In 2025, the picture is more developed. The question is no longer only whether operators are reporting, but what the reports show about compliance behaviour and justification quality. That is where this year’s verified information becomes useful.
17 Jun 2026
Navigating SAF documentation: Common challenges and best practices
As Sustainable Aviation Fuel (SAF) adoption continues to grow under Aviation Regulations, documentation quality and traceability have become key areas of focus during reporting of SAF and verification activities. While SAF offers significant environmental benefits, demonstrating compliance requires operators to maintain accurate, complete, and verifiable records throughout the reporting period.
Based on our experience supporting aviation stakeholders with compliance and verification activities, several recurring challenges have emerged. Fortunately, many of these issues can be addressed through early planning and proactive engagement with fuel suppliers and competent authorities.
01 May 2026
EU Launches Carbon Removal Certification Framework (CRCF)
The European Union has taken a significant step toward achieving climate neutrality with the adoption of Regulation (EU) 2024/3012, establishing the Carbon Removal Certification Framework (CRCF).
01 May 2026
CSRD Scope Narrowed: But Are You Still Required to Verify Sustainability Reporting?
The European Commission’s Omnibus “Content Directive” entered into force on 18 March 2026, bringing final clarity to the Corporate Sustainability Reporting Directive after more than a year of negotiation. EU Member States now have until 19 March 2027 to transpose the changes into national law. For organisations subject to CSRD, this is the moment to adjust your verification planning with confidence. The question is no longer whether CSRD will apply it is whether your organization remains in scope, and if not, whether voluntary verification still serves your business objectives.
01 May 2026
ETS 2 First Verification Cycle Complete: Lessons from Early Implementation
ETS 2 verifications have now been completed for the first reporting cycle, marking an important milestone in the expansion of the EU carbon market to transport and building fuels.
Sign up for the newsletter
Stay up to date on the latest news, exclusive updates, and valuable insights.